

US homeowners doubt election will cut rising housing costs
Fri, 6th Nov 2026 (Today)
Hometap's survey found that 77% of US homeowners could be swayed by a candidate's plan to cut household costs, but only 26% believe a candidate could actually deliver that relief.
The findings point to a gap between the political salience of housing affordability and homeowners' confidence that elected officials can reduce the cost of keeping a home.
According to the survey, 63% of homeowners said owning a home causes at least moderate financial stress, up from 55% in a previous Hometap survey last year. Another 71% said they expect homeownership costs to keep rising regardless of the election result.
The figures suggest concern has shifted beyond mortgage rates and house prices to the recurring expenses that follow a purchase. Taxes were the top voting issue for 35% of respondents, while 75% said their property tax bill had risen in the past two years.
Even so, 51% said they did not know of a property tax measure on their ballot. Statewide property tax questions were due to go before voters in several states.
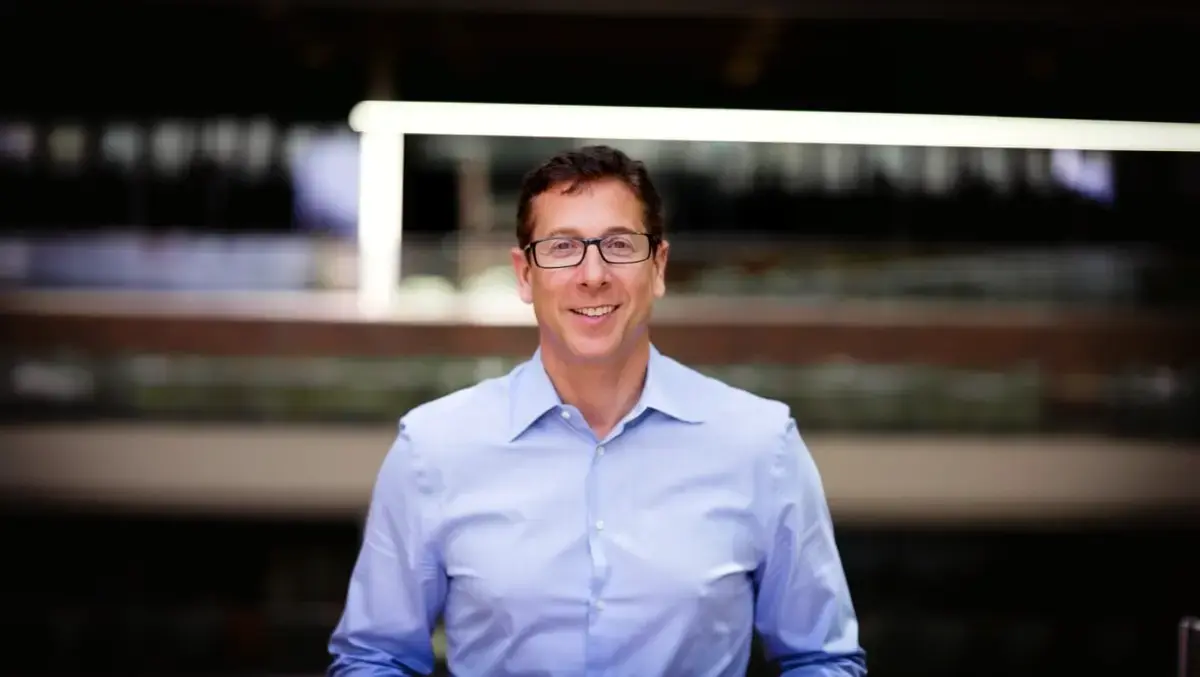
Jeff Glass, chief executive officer of Hometap, said the survey showed a mismatch between the political debate and homeowners' day-to-day concerns. "Affordability is on the ballot this year, but almost all of the conversation is about getting people into homes," he said.
"Homeowners are telling us there's a different affordability challenge: staying in one. Property taxes, insurance, and upkeep keep climbing, and most of them don't believe the election will change that. Policy has a role to play, but while policymakers continue to tackle affordability, homeowners deserve more options to put the wealth they've built in their homes to work against rising costs."
Stress levels
The survey also showed a sharp age divide. Among Millennial homeowners, 77% said they were at least moderately stressed by the cost of ownership, compared with 48% of Baby Boomers. Younger owners were also more likely to say these costs felt increasingly outside their control, at 62% versus 44%.
Financial strain appeared to spill into other parts of life. Among the most stressed homeowners, 92% said that strain affected their daily lives, including 57% who reported symptoms of anxiety or depression, 52% who said they had trouble sleeping, and 33% who said they had delayed medical or dental care.
Utilities were cited as the most stressful homeownership cost by 31% of respondents. Maintenance and repairs came next at 17%, ahead of mortgage payments at 10% and insurance at 9%.
That ordering underlines how the economics of homeownership can differ from the public debate, which often centres on borrowing costs. For existing owners, routine bills and unexpected repair costs may weigh more heavily than loan repayments.
Mobility questions
Hometap said 46% of homeowners had considered moving because of state policy, but fewer than 2% had actually done so. That suggests frustration with taxes and other costs does not easily translate into relocation, even when households believe policy choices are affecting affordability.
Glass said property tax bills can directly affect family decisions. "Property tax policy can feel abstract until the bill lands on the kitchen table," he said.
"For homeowners, property taxes shape where they live, how long they stay, and the trade-offs they have to make to sustain homeownership. These aren't just budget decisions; they're decisions about the life a family gets to live."
The survey also found that home equity was not a main source of financial security for many respondents who did not feel financially stressed. Among that group, 24% pointed to home equity, compared with 42% who cited stable income, 37% who cited a paid-off mortgage, and 35% who cited savings.
AYTM conducted the poll on behalf of Hometap among 1,000 US homeowners. The results carried a 95% confidence level and a margin of error of plus or minus 3 percentage points.